BOJ policy normalisation: expected path and oil-related risks
The Bank of Japan (BOJ) is currently undertaking gradual monetary policy normalisation, with the policy rate remaining significantly below the prevailing inflation rate after the central bank started the process from an exceptionally accommodative position. In principle, a policy rate above 2% could be justified if inflation at that level were seen as durable. However, the BOJ is not expected to pursue a high terminal rate. Structural factors—most notably demographic decline—mean that Japan continues to face fundamental challenges in sustaining inflation over the medium to long term. As a result, consensus expectations remain anchored on a terminal policy rate below 2%. The BOJ’s own confidence in inflation being sustained over the longer-term is likely limited, reinforcing expectations of a shallow hiking cycle.
Developments in oil markets in the wake of the conflict in the Middle East are expected to test the BOJ’s normalisation process. We see three broad scenarios framing investor thinking.
In the base case, any disruption to oil supply is temporary. Even if tanker traffic through key routes is interrupted for several weeks, Japan’s substantial oil reserves—estimated at roughly 250 days—would limit the impact on production. While oil prices may rise for a period, the resulting inflationary pressure would be limited and insufficient to materially damage the broader economy. Under this scenario, monetary policy would remain on its current path.
A second scenario involves a more prolonged period of elevated oil prices without a corresponding rise in wages or labour shortages strong enough to cushion the blow. In this case, higher energy costs would crowd out discretionary spending, leading to weaker consumption and lower trend growth. This outcome would be characterised less by inflation than by a consumer‑led slowdown. This would not result in stagflation because households’ reduced purchasing power would limit price increases elsewhere in the economy, and higher oil prices would not translate into higher incomes.
The third possibility—a sustained supply shock in which oil inflows effectively dry up for six months or more—would represent a genuine negative supply shock like the one witnessed during the pandemic period. While this could trigger a recession, it would not necessarily produce sustained inflation. Such a scenario would require a governmental response, such as adjustments to Japan’s energy mix, rather than monetary policy alone.
Geopolitical considerations, including US strategic interests, currently limit the likelihood of a prolonged shutdown of oil supply routes. Consequently, the market’s central scenario remains that any oil‑related inflation proves temporary and gives way to softer growth rather than persistent price pressures. Under this baseline, the BOJ’s expected policy path remains mostly unchanged, with one rate hike in 2026, followed by another in early 2027 (January–March). If higher energy costs weigh on household spending and consumption weakens substantially as a result, the BOJ may pause on further tightening and potentially reassess its stance.
Crucially, the risk of Japan experiencing entrenched stagflation is limited. Japan’s dependence on oil has declined significantly since the 1970s. Even in the event of higher oil prices, the more probable outcome is slower growth rather than an inflationary spiral requiring aggressive monetary tightening.
Wages, oil prices, and the sustainability of domestic demand
Japan is currently experiencing the most meaningful change in wage dynamics for the first time in decades, one that is driven by stronger corporate sales rather than by cost‑push inflation. The starting point of the wage cycle was robust demand. Exports have recovered after the pandemic, domestic sales volumes have risen and Japan Inc. is facing persistent labour shortages. Under these conditions, companies are able to raise wages and maintain profitability; they can also increase capital expenditure to substitute for limited labour. Wage growth, therefore, is emerging on the back of strong demand rather than due to policy intervention.
Over the past two years, inflation rose substantially while wage growth lagged, resulting in weak real income growth and subdued consumption. However, the tide now appears to be turning. Inflationary pressures are expected to moderate—the BOJ’s CPI projections are around 1.9%, with market consensus pointing to a gradual deceleration—while labour shortages remain. Importantly, wage settlements in the current fiscal year point to further nominal wage gains. This creates the conditions for sustained real wage growth for the first time in recent memory, marking a potential beginning for consumption-led growth in Japan.
It is worth noting that amid a spike in energy prices due to geopolitical tensions in the Middle East, a sustained rise in real wages would be largely independent of oil prices. The key question is not whether costs can always be passed through, but whether Japan can transition toward a more conventional growth model in which domestic demand plays a central role. For the first time since the Global Financial Crisis, consumption has a chance of contributing meaningfully to growth. Stronger sales enable firms to hire more and increase wages; continued labour shortages reinforce upward wage pressure; and higher income feeds back into consumption, forming a self‑reinforcing cycle.
Geopolitical risks in the Middle East should be viewed primarily in terms of their effect on consumer psychology rather than as a potential driver of sustained inflation. Higher oil prices may raise the cost of essentials and weaken household sentiment instead of generating price pressures. In the near term, such shocks could produce a brief inflationary spike as households dip into savings. Once that adjustment passes, the more likely outcome is softer growth and disinflationary pressure.
From a policy perspective, oil‑driven price increases thus pose a risk for the effect they may have on the virtuous wage–consumption cycle rather than as a possible catalyst for sustained inflation. If higher energy costs weaken consumption and household confidence, the result would be a deterioration in growth. This, in turn, would put interest rates under downward pressure instead of providing the BOJ with a justification for further rate hikes.
Japanese stocks fall in March on concerns of heightened inflationary pressure
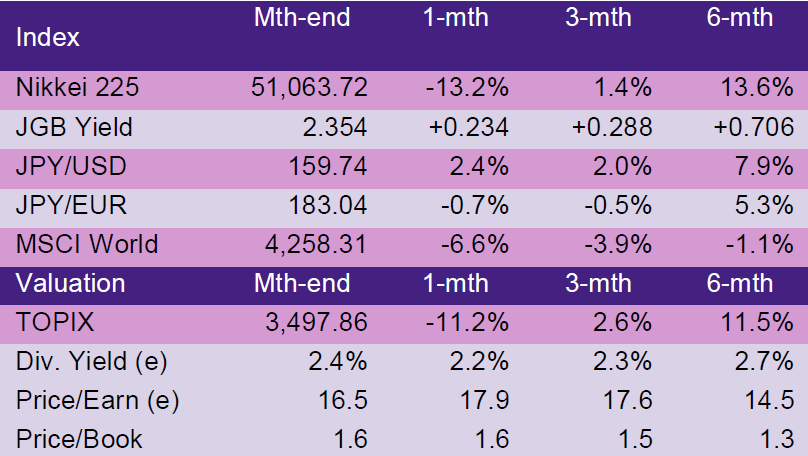
The Japanese equity market ended March lower with the TOPIX (w/dividends) down 10.33% on-month and the Nikkei 225 (w/dividends) falling 12.64%. A number of factors weighed down the market, including heightened inflationary pressure stemming from higher crude oil prices amid concerns over a prolongation of the Iran conflict. At the same time, rate cut expectations waned after the outcome of the Federal Open Market Committee meeting, and as the BOJ implied that rising oil and a weaker yen could further drive inflation, bringing the possibility of early rate hikes into focus.
Of the 33 Tokyo Stock Exchange sectors, only two sectors rose: Mining and Marine Transportation. The remaining 31 sectors declined, with Air Transportation, Rubber Products, and Machinery seeing the steepest drops.
Exhibit 1: Major indices
Source: Bloomberg, 31 March 2026
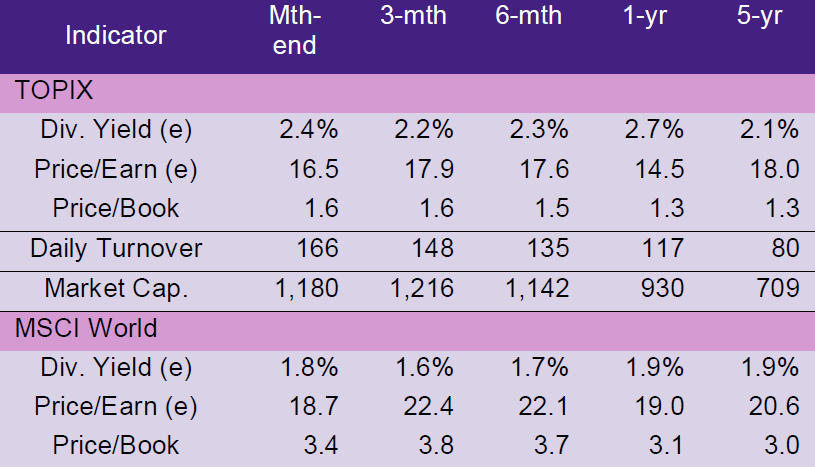
Exhibit 2: Valuation and indicators